cz
European Agricultural Machinery Market Continues to Weaken. CLIMMAR Index Hits an All-Time Low
26. 10. 2026The economic situation of European agricultural machinery dealers deteriorated further in the first half of 2026. The CLIMMAR Index, which tracks developments across the sector in European countries, fell to an all-time low of −0.89 points. The greatest difficulties remain in new machinery sales, but the downturn is increasingly affecting workshop services and spare parts sales as well. Expectations for the second half of 2026 also point to no improvement.
The results were presented at the annual congress of the European organisation CLIMMAR, held in Bruges, Belgium, in October 2026. The regular CLIMMAR Branch Report monitors the economic performance of agricultural machinery dealers across member countries. The survey covers turnover, operating costs, employment, inventories, investments and expectations for future developments.
CLIMMAR Index reaches an all-time low
The overall CLIMMAR Index stood at −0.89 points in the first half of 2026, its lowest level since the index was introduced.
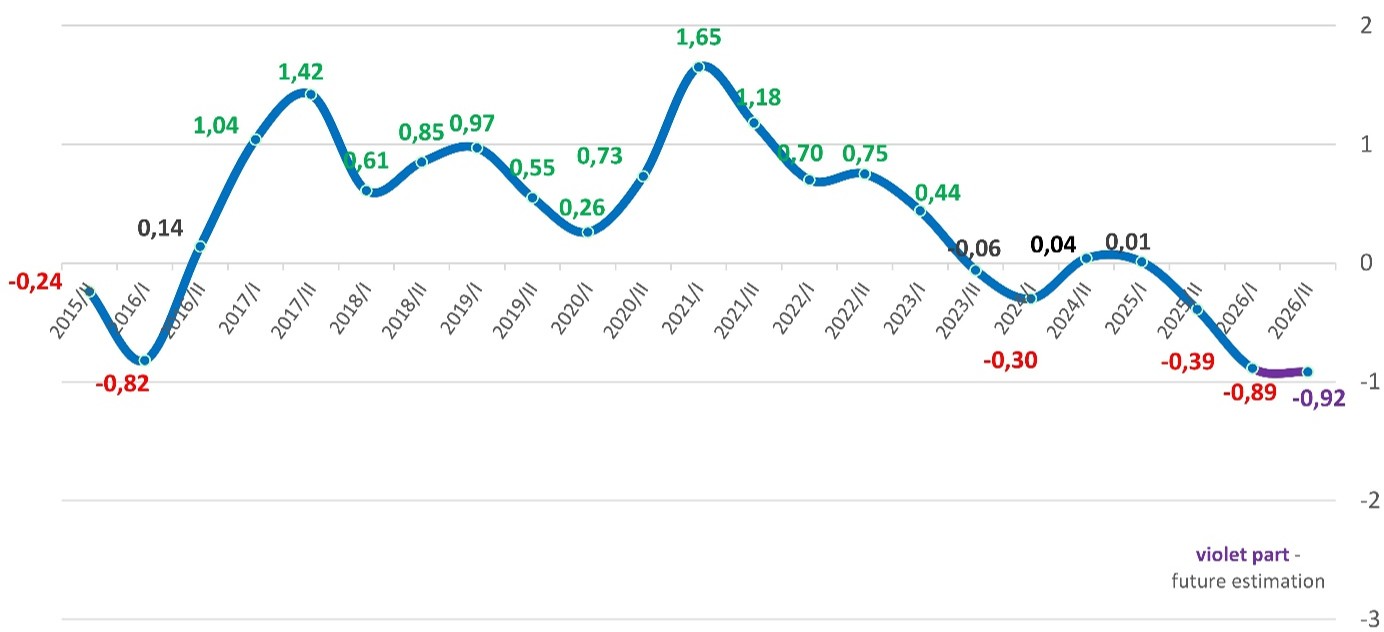
The index reflects the overall economic situation of European agricultural machinery dealers on a scale from −3 to +3 points. It is based on a weighted assessment of turnover trends across individual business segments and expectations for future turnover.
Following the market recovery in 2020–2021, conditions gradually deteriorated. The brief stabilisation observed in 2024 and 2025 did not develop into a sustained recovery.
The outlook for the second half of 2026 is slightly more pessimistic. The expected CLIMMAR Index stands at −0.92 points, suggesting that the negative trend is likely to continue.
New machinery sales remain the weakest segment
New agricultural machinery sales continue to face the greatest difficulties. The index for this segment reached −2.1 points in the first half of 2026, indicating a strongly negative assessment of turnover compared with the same period in 2025.
Declining new machinery sales were reported in 12 of the 16 countries surveyed. Only two countries recorded growth, while another two reported stagnation. Negative trends are evident across most major European markets, including Germany, France, Italy and the Czech Republic.
Conditions in the used machinery market also remain unfavourable, with the trend index reaching −1.1 points. A further deterioration to −1.6 points is expected in the second half of the year.
The stabilising role of workshop services and spare parts is weakening
One of the concerning findings of this year's survey is the gradual deterioration in workshop services, which have traditionally provided agricultural machinery dealers with a more stable source of revenue.
While turnover from servicing and spare parts was able to partially offset declining machinery sales in previous years, growth in these activities is now slowing significantly.
In the first half of 2026, the trend index for workshop services stood at +0.4 points, while spare parts sales moved slightly into negative territory (−0.1 points).
Expectations for the second half of the year are negative in both segments. The index is forecast to reach −0.2 points for workshop services and −0.6 points for spare parts sales.
If these expectations materialise, dealers will lose part of the stabilising effect of after-sales activities, which have long played an important role in their overall economic performance.
Negative trends prevail across Europe
The results show that the difficulties are not limited to a handful of individual markets. In the first half of 2026, 11 of the 16 countries surveyed reported a decline in total turnover, four recorded stagnation, and only Sweden reported growth. A further decline in total turnover is expected in 12 of the 16 countries.
The Czech Republic is also among the countries experiencing negative developments. The domestic market recorded declining sales, and expectations for the second half of the year are no more favourable.
CLIMMAR represents more than 15,000 European dealerships
According to updated figures from the 2026 Branch Report, CLIMMAR's member associations represent a total of 15,197 sales and service businesses, employing approximately 187,000 people and generating combined annual turnover of nearly EUR 49 billion.
CLIMMAR's regular economic survey is an important tool for monitoring developments in the European market, comparing conditions across countries and identifying common challenges facing the industry.
The latest findings indicate that the European agricultural machinery dealership sector has not yet reached a turning point. Alongside the continuing decline in new machinery sales, the slowdown in after-sales activities and pressure from rising operating costs are becoming increasingly apparent. The combination of weak turnover, rising operating costs and limited investment places a considerable financial burden on European sales and service businesses.
Source: CLIMMAR Branch Report 2026-I, CLIMMAR Markets & Data Working Group.